

Business Operation · 2025
In this section24 topics
- Corporate Information4 items
- Dividend Policy2 items
- Major Shareholders3 items
- Business Strategies Overview4 items
- Material Changes & Developments1 item
- Use of Proceeds from Securities Offerings1 item
- Commitments Made in the Registration Statement1 item
- Group Operating-Structure Policy1 item
- Companies Where the Company Holds ≥10%1 item
- Shareholders with Potential Conflict of Interest1 item
- Relationships Among Major Shareholders2 items
- Shareholders' Agreement1 item
- Shareholding Diagram (Group Structure)2 items
- Income Structure4 items
- Product / Service Characteristics3 items
- Research & Development2 items
- Assets Used in the Business6 items
- Marketing Policy & Competition3 items
- Procurement of Products & Services2 items
- Product Information — Overview1 item
- Projects Under Construction2 items
- Issuance of Other Securities1 item
- Debentures & Bills of Exchange1 item
- Convertible Securities1 item
Corporate Information
Company Name
THAIRE LIFE ASSURANCE PUBLIC COMPANY LIMITED
Telephone
0-2666-9000
Website
www.thairelife.co.th
mailbox@thairelife.co.th
Dividend Policy
Dividend Policy
We have a policy to pay dividends at not less than 40 percent of net profit from the separate financial statement after corporate income tax and all types of reserves as required by law and as specified in the Company’s Articles of Association. However, the dividend payment is subject to change as deemed necessary and appropriate by the Board of Directors. The Company’s dividend payment must be approved by OIC pursuant to Section 32 of the Life Insurance Act B.E. 2535. (and the subsequent amendments)
Historical Dividend Payments
| This Year | Last Year | 2 Years Ago | 3 Years Ago | 4 Years Ago | Metric | Description |
|---|---|---|---|---|---|---|
| -0.12 | -0.14 | 0.1 | 0.26 | 0.16 | Net profit per share (Baht : Share) | Net profit per share (baht : share) |
| 0 | 0 | 0.07 | 0.15 | 0.12 | Dividend per share (Baht : Share) | Dividend per share (baht : share) |
| 0 | 0 | 61 | 60 | 0 | Dividend stock ratio (Number of original shares: dividend shares) | Ratio of stock dividend payment (existing share : stock dividend) |
| 0 | 0 | 0.02 | 0.02 | 0.12 | Dividend share value per share (Baht : Share) | Value of stock dividend per share (baht : share) |
| 0 | 0 | 0.09 | 0.17 | 0.12 | Total dividend payment value (Baht : Share) | Total dividend payment (baht : share) |
| 0 | 0 | 84.85 | 65.31 | 73.1 | Dividend payout ratio to net profit (%) | Dividend payout ratio compared to net profit (%) |
Business Strategies Overview
Vision
"Being Unique Life Reinsurance Solutions Provider"
Objectives
Apart from the core business in providing all types of life and health reinsurance, the Company sets aside part of the written premiums as reserves and invests such amount to generate returns to cover its contingent liabilities. Therefore, investment also plays a crucial part in the Company’s core activity.
The Company diversifies its investment in a variety of short-term and long-term securities, both debt and equity instruments, and complies with regulations under the Office of Insurance Commission (OIC): Notification Re: Investment in Other Businesses of Life Insurance Companies.
Goals
The Company aspires to continuously develop its organization, operating systems, and personnel to achieve its goal of being more than just a traditional reinsurance provider. We aim to offer comprehensive services to life insurance company customers, including reinsurance, business development, marketing planning, product development, and advice on underwriting and claim guidelines.
Additionally, the Company focuses on continuously studying consumer behavior and market conditions to advance the reinsurance business. We collaborate with local and international partners to develop life insurance products that meet the diverse needs of consumers, covering life, accident, credit, and health protection, as well as critical illnesses and modern medical treatment innovations.
Business Strategies
The Company has developed action plans to align with its strategy as follows:
1) For its reinsurance business plan, the Company focuses on expanding coverage for each product while emphasizing quality and sustainable growth. This is achieved by managing expansion costs in line with Insurance Risk-Based Capital and considering the return on capital based on acceptable risk levels. The Company aims to align its business development with changes in the life insurance industry and consumer needs, study new innovations for marketing planning, and develop products suitable for various sales channels to cover all customer groups.
2) operational support plan, the Company has invested in technology systems for enterprise data management and adjusted various work processes to comply with the new International Financial Reporting Standards (IFRS17), effective from January 2025.
3) Developing the skills and knowledge plan of its personnel to keep pace with the rapid changes in the insurance industry and to handle potential future crises. The Company also seeks to recruit experienced individuals with fresh ideas to enhance operations and build a high-quality team, aiming for sustainable business growth.
Material Changes & Developments
Material Changes & Developments
| Year | Description |
|---|---|
| 2,023 | Focus development on health reinsurance expansion under the focus on ESG (Environmental, Social, and Governance) and granted Thailand Sustainability Investment (THIS) Award with SET ESG rating in A Class from The Stock Exchange of Thailand (SET) and 5-stars rating on the list of company governance ‘CGR’ from Thai Institute of Directors (IOD) The company obtained a financial credit rating from the International Credit Rating Agency: A.M. Best in Best's Financial Strength: B++ (Good) which has been downgraded due to the company's performance declining from the impact of increased claims for health insurance products as many people return to the hospital after treatment. The outbreak of Covid-19 and the increase in the cost of medical treatment (Medical Inflation) |
| 2,024 | The Company is committed to sustainable growth by adjusting its product mix and reinsurance conditions, while conducting business with a focus on environmental, social, and governance (ESG) principles. This includes prioritizing all stakeholders, such as employees, communities, and society, throughout our business processes. The Company has been recognized as a "Sustainable Stock" with an SET ESG Rating of level A from the Stock Exchange of Thailand for three consecutive years. Additionally, we have received a 5-star corporate governance assessment score, or "Excellent" (Excellent CG Scoring), for eight consecutive years and have been named one of the TOP QUARTILE COMPANIES in 2024 for the second consecutive year. Furthermore, the Company has relocated to the Sathorn Thani 2 Building, a strategic location in the heart of the city, close to both domestic and international partners. |
| 2,025 | The Company aims to continuously manage its product mix and reinsurance underwriting terms to ensure operating performance remains in line with its business plans. The Company conducts its operations under a framework that gives due consideration to Environmental, Social, and Governance (ESG) principles, with a strong focus on all stakeholders, including the ongoing prioritization of shareholder interests. In this regard, the Company was honored with the Outstanding Investor Relations Award at the SET Awards 2025, organized by the Stock Exchange of Thailand and Money & Banking Magazine. This award reflects the Company’s commitment to transparent, effective, and well-governed investor relations practices, as well as its adherence to sound corporate governance principles in communicating with shareholders, investors, and all stakeholders. |
Use of Proceeds from Securities Offerings
Is There Money Raised from a Securities Offering Still to Report On?
No
Commitments Made in the Registration Statement
Are There Commitments or Conditions from an Offering or Listing?
No
Group Operating-Structure Policy
Description
The Company has a clear shareholding structure and there is no cross-shareholding or pyramid structure in its group of companies, thus creating no conflict of interest. Entering into related party transactions, the Company has complied with the policy on interest and conflict of interest and the measures or procedures for approval of related party transactions.
The Company has one associated company, TKI Investment Company Limited (former TKI Life Insurance Company Limited), established in Lao PDR in late 2016 to perform all types of life insurance business. Its total paid-up registered capitals are LAK 16,000 million or approximately THB 66 million of which the Company holds 32.5 per cent shares.
Companies Where the Company Holds ≥10%
Companies (≥10% Holding)
| Company Name | Address | Province | Zip Code | Telephone | Fax | Business Type | Security Type | Shares | Paid-up Shares |
|---|---|---|---|---|---|---|---|---|---|
| TKI Investment Company Limited | Level 4, Zone A office Unit, The Iconic, Unit 11, Phonxay Road, Phonxay Village, Saysettha District, Vientiane Capital 01000 Lao PDR. | Foreign country | 01000 | 856-21417707 | 856-21417705 | To engage in the business of holding shares in other enterprises. | Common shares | 8,000,000 | 8,000,000 |
Income Structure
Introduction
The Company’s revenue structure reflects the nature of its operations and is classified into three principal categories: reinsurance revenue, investment income, and other income. Reinsurance revenue is derived from both domestic and overseas operations, whereas investment income and other income are generated from domestic operations.
The table below presents the Company’s revenue structure for the financial years 2024 and 2025, prepared in accordance with Thai Financial Reporting Standard No. 17: Insurance Contracts (“TFRS 17”). The Company adopted TFRS 17 effective 1 January 2025 and has restated and reclassified the financial information for the financial year 2024 for comparative purposes. Revenue structure information for the financial year 2023, which was prepared in accordance with Thai Financial Reporting Standard No. 4: Insurance Contracts (“TFRS 4”), is not presented as comparative information.
Product / Service Income
| Category | Description | This Year | This Year % | Last Year | Last Year % | 2 Years Ago | 2 Years Ago % |
|---|---|---|---|---|---|---|---|
| Total revenue from operations | Total revenue from operations | 2,602,610.73 | 100 | 2,749,092.73 | 100 | 0 | 0 |
| Insurance Revenue | 2,539,005.15 | 97.56 | 2,676,092.79 | 97.34 | 0 | 0 | |
| Net Investment Income | 62,680.35 | 2.41 | 70,409.63 | 2.56 | 0 | 0 | |
| Other income | 925.22 | 0.04 | 2,590.31 | 0.09 | 0 | 0 | |
| Other | Other |
Export Income
| Category | Description | This Year | This Year % | Last Year | Last Year % | 2 Years Ago | 2 Years Ago % |
|---|---|---|---|---|---|---|---|
| Total revenue | Total revenue from operations | 2,602,610.73 | 100 | 2,749,092.73 | 100 | 0 | 0 |
| Domestic | Domestic | 2,569,803.43 | 98.74 | 2,405,264.53 | 87.49 | 0 | 0 |
| International | International | 32,807.3 | 1.26 | 343,828.2 | 12.51 | 0 | 0 |
Other Income
| Operating Other Income | Non-Operating Other Income | Share of Profit |
|---|---|---|
| 1710 · As of year: 925.22 · Description: Total other income · As of yesteryear: 2590.31 · As of year before yesteryear: 0.0 · 1711 · As of year: 925.22 · Description: Other income from operations · As of yesteryear: 2590.31 · As of year before yesteryear: 0.0 | 1712 · As of year: 0.0 · Description: Other income not from operations · As of yesteryear: 0.0 · As of year before yesteryear: 0.0 | 1713 · Description: Share of profit |
Product / Service Characteristics
Introduction
Reinsurance Business by Marketing Policy can be categorized into 2 types as follow:
Business Type
3115
Business Groups
| Business Group | Description |
|---|---|
| Conventional Reinsurance | Conventional reinsurance is the reinsurance service that all arrangements are made by life insurance companies, ranging from product development, marketing and sales of products. Risks associated with the sum insured are allocated to several reinsurers both local and overseas. Conventional reinsurance is considered to be “Passive Reinsurance” where reinsurance companies don’t take any part of Insurers’ product development. The Company has developed conventional reinsurance business and maintained its growth through value added services such as providing product consultation, joint development for additional underwriting guidelines, and provision of underwriting services as well as other technical knowledge in relation to life insurance business. |
| Non-conventional Reinsurance | The Company has taken proactive approach in capture market share in Thailand since Thai reinsurance market is an open market where any reinsurers can enter at any time. The Company has taken role as an active reinsurer by participating in all activities with life insurance companies, ranging from market demand assessment, new product development, set up marketing activities as well as exploring new distribution channels. By taking an active role, the Company can design appropriate policies and determine suitable pricing; as a result, which enable the company to qualify for higher underwriting quota sharing percentage than conventional reinsurance. Managing health and medical cost has been a focusing trend for people to seek for healthcare coverage. The Company has continuously implemented several joint development projects with insurance companies by focusing on product development through various channels. By understanding different target groups, our key focus areas on product development have been on senior needs, health and critical illness, with additional development on mental illness. |
Research & Development
Has R&D Policy (Y/N)
No
R&D Cost — Label
Research and development (R&D) expenses over the past 3 years (Million Baht)
Assets Used in the Business
Permanent Assets — Description
As of December 31, 2025, the Company has fixed assets of the type; leasehold improvements and equipment. The net book value total amount 18.9 million baht or 0.8% of total assets as the following details.
Permanent Assets — Appraisal
| Asset | Ownership | Obligation | Appraisal Value |
|---|---|---|---|
| Buildings | lease | none | 4,416,214 |
| Rental building improvements | owner | none | 9,103,438 |
| Furniture, fixture and equipment | owner | none | 1,268,820 |
| Computer | owner | none | 2,517,967 |
| Vehicle | lease | none | 1,561,040 |
Intangible Assets — Description
As of December 31, 2025, the Company has intangible assets used in its operations, consisting of computer software. The net book value total amount 36.5 million baht or 1.5% of total assets as the following details.
Intangible Assets — Appraisal
| Asset | Type | Appraisal Value |
|---|---|---|
| Computer Software | Software | 36,503,558 |
Has Subsidiaries Investment Policy (Y/N)
Yes
Subsidiaries Investment Policy — Description
The Board of Directors approves the investment policy in associated companies. According to the recommendation of the Investment Committee by making investment decisions and approval of the transaction in accordance with the criteria set by the SEC Office, the Stock Exchange of Thailand and the Office of Insurance Commission.
The Company has a mechanism to supervise the operations of associated companies by appointing directors and executives of the company to be directors and executives of the associated company by persons appointed as directors and executives of subsidiaries and associated companies It is responsible for supervising, controlling, and monitoring operations for the benefit of the business for that company and the company itself.
Marketing Policy & Competition
Reporting Mode
3117
Marketing Policy (Overall)
During the past year, the Company remained committed to implementing marketing strategies to respond to changes in the economic environment, technological advancements, and evolving customer behaviors. Emphasis was placed on the development of products and services that address increasingly diverse and specific customer needs.
The Company also sought opportunities to expand into new markets, while establishing and strengthening partnerships with new business partners to enhance its customer reach and competitive capabilities. Such initiatives aim to support sustainable growth and create long-term value for all stakeholders.
Industry & Competition (Overall)
Life Insurance and Reinsurance Market Situation in 2025
In 2025, Thailand continued to operate under an environment of economic uncertainty, driven by global economic volatility, geopolitical tensions, climate change impacts, rising medical inflation, and a downward interest rate trend. These factors directly affected household saving, investment, and spending behavior. Thailand’s economic growth moderated during the year, while elevated household debt levels constrained the recovery of consumer purchasing power. At the same time, financial institutions maintained a cautious approach to lending, resulting in the Thai life insurance industry recording only modest growth compared to the previous year.
In terms of product segments, credit-related life insurance products distributed through bancassurance channels continued to face limitations due to the slowdown in loan growth. In contrast, protection-oriented products, particularly health insurance and critical illness coverage, remained key growth drivers of the industry. This was supported by heightened awareness among both the aging population and younger generations regarding the importance of life and health insurance, as well as long-term financial planning, under the objective of preparing for future expenses and ensuring long-term quality of life. Nevertheless, rising healthcare costs and persistent medical inflation continued to exert upward pressure on health claim costs, presenting a significant challenge for life insurers in managing risks and setting premiums at sustainable and appropriate levels.
As a result, life insurance companies adjusted their sales and service strategies to better align with evolving consumer behavior, while focusing on the development of products that deliver long-term value. Insurers also expanded distribution channels and increasingly adopted digital technologies across operational and service processes to enhance efficiency and competitiveness.
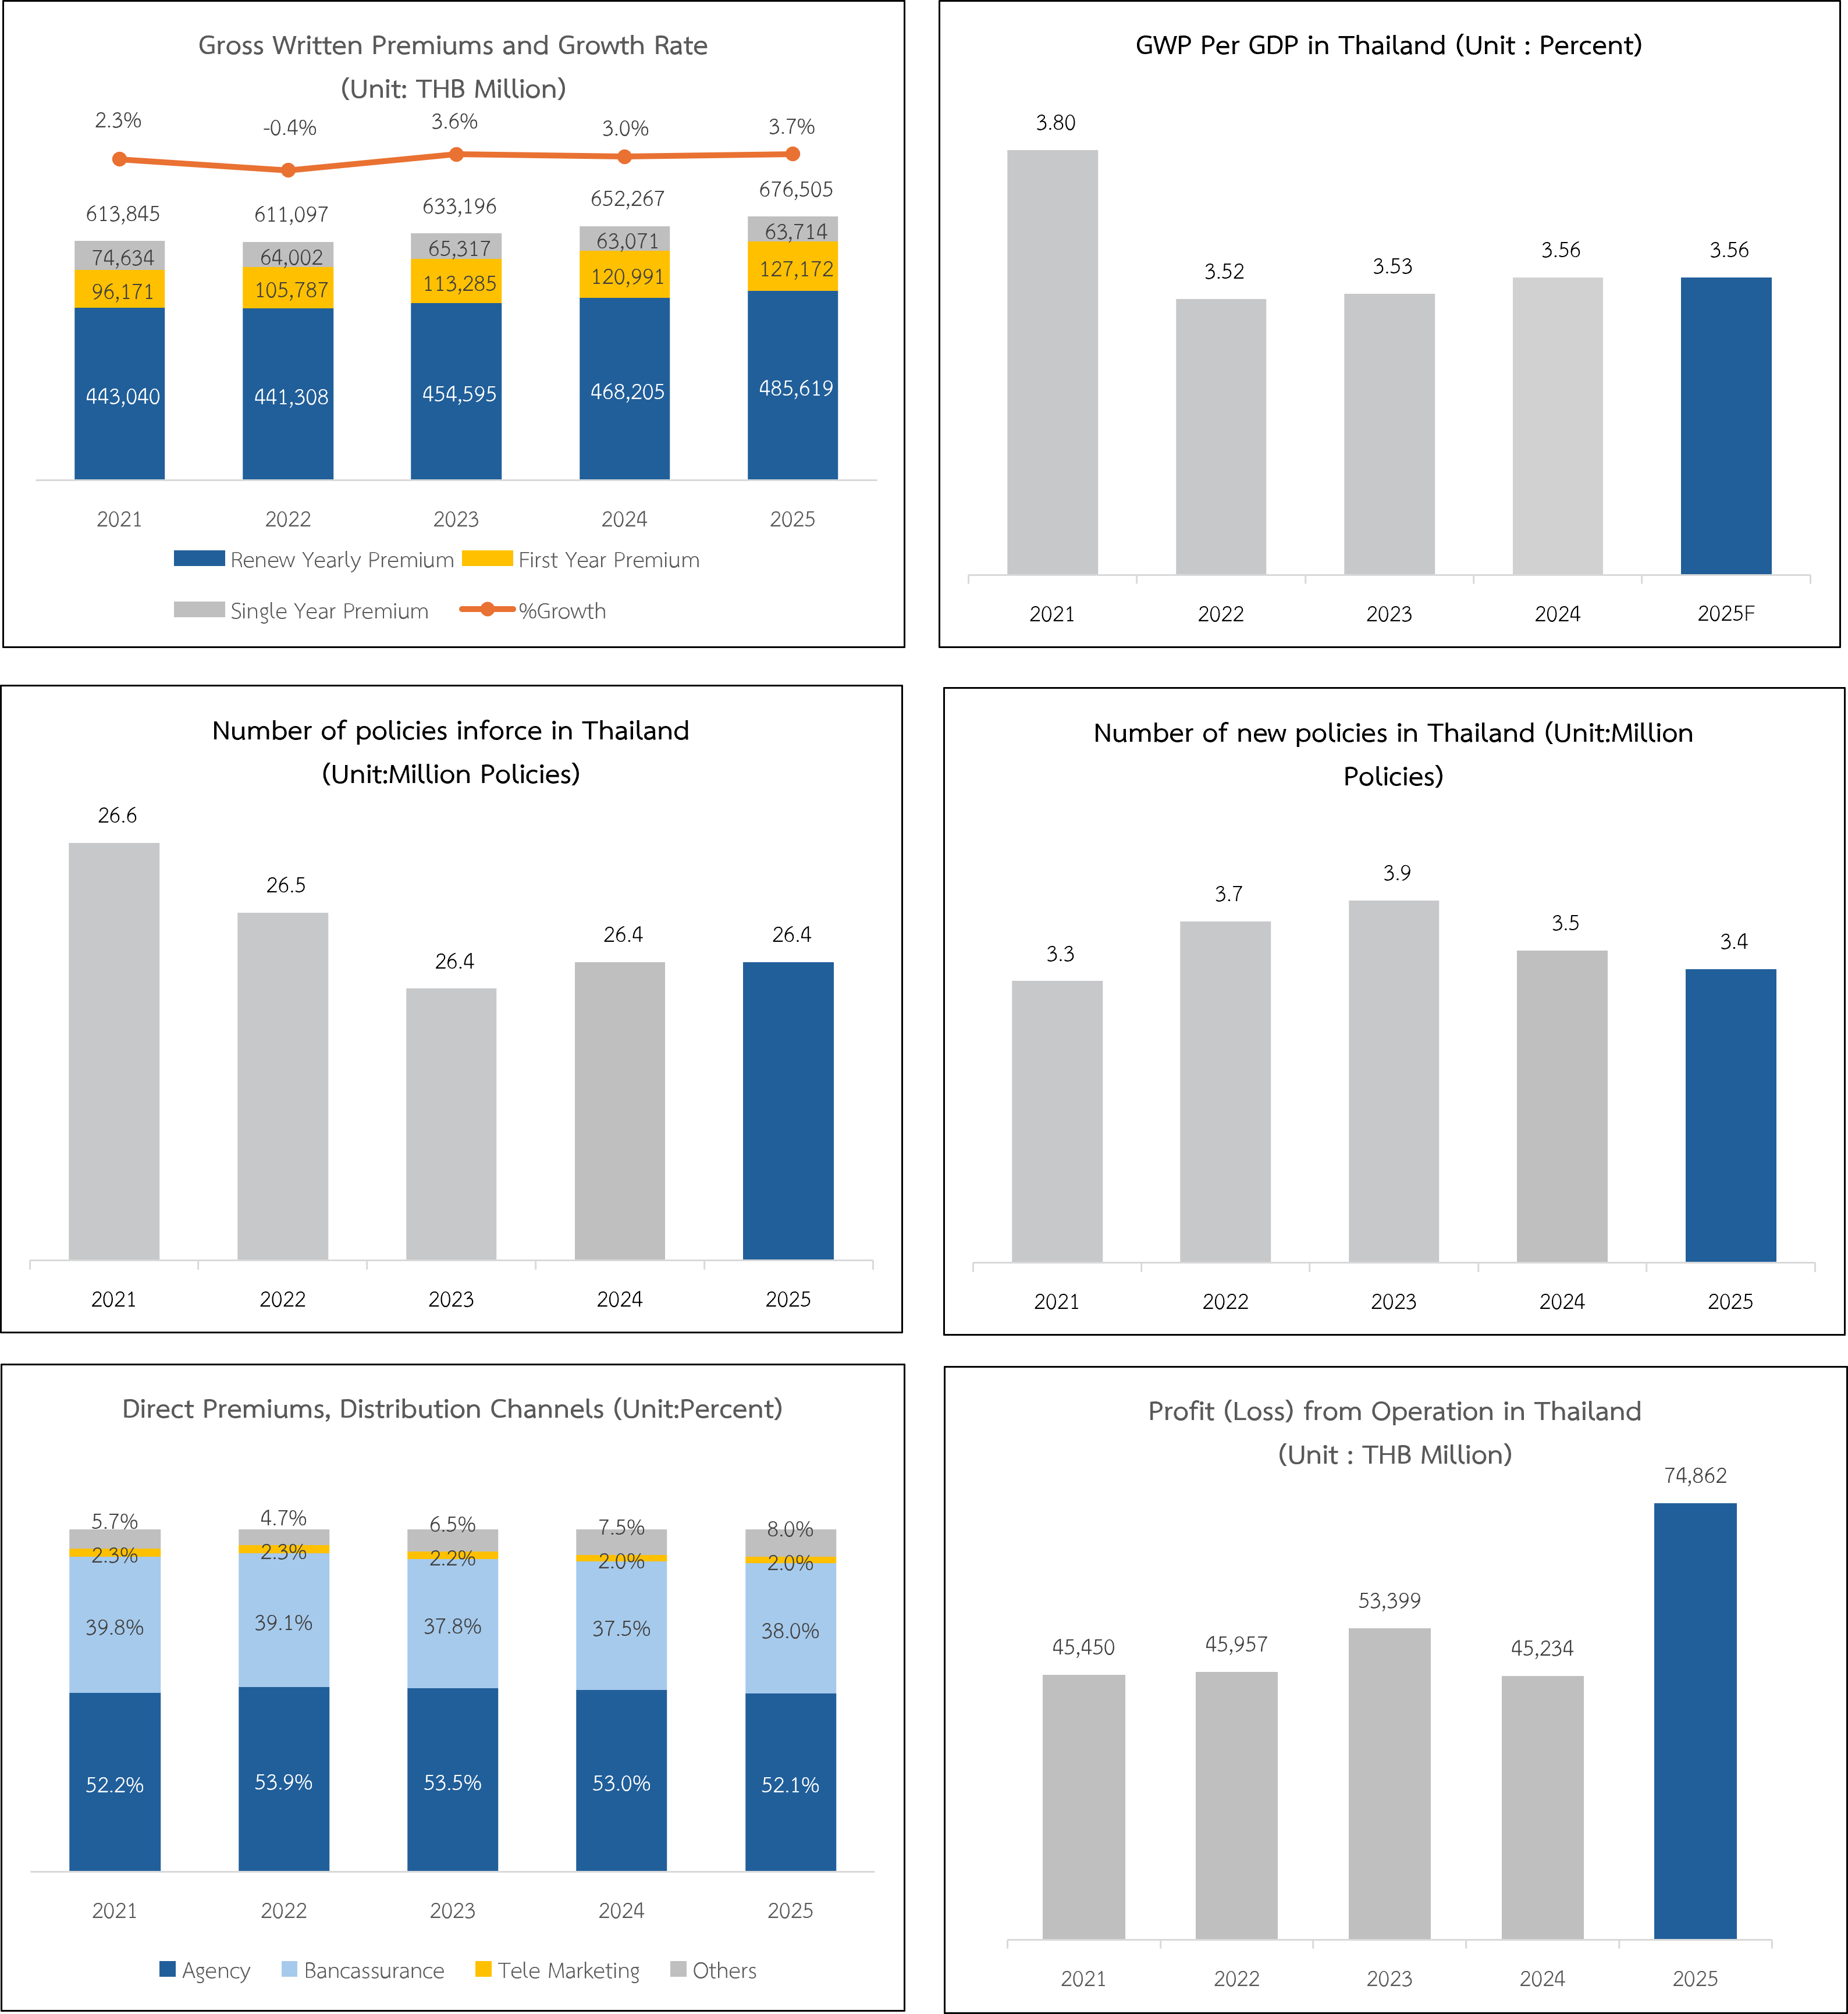
Based on these factors, total written life insurance premiums in Thailand in 2025 are expected to increase slightly from the previous year of THB 676,505 billion, representing growth of 3.45%. The ratio of net life insurance premiums to gross domestic product (GDP) is projected to remain at approximately 3.5–3.7%, reflecting the continued importance of the life insurance industry to Thailand’s economic system.
Life insurance business statistics data for 2020 – 2024 (Market Data)
In 2025, reinsurance ceded premiums amounted to THB 40,105 million, reflecting an annual growth rate of 15 percent, consistent with the double-digit growth seen in previous years. Most of these premiums stemmed from ordinary life and health insurance products. Reinsurance ceded premiums represent 5.9 percent of gross written premiums. Despite the relatively low reinsurance ratio compared to international standards, reinsurance remains a key strategy for life insurers in managing insurance risk. Consequently, reinsurance premium growth typically mirrors growth in the direct insurance sector. Over the past five years (2021-2025), reinsurance premiums have grown at an average annual rate of 18.1 percent.
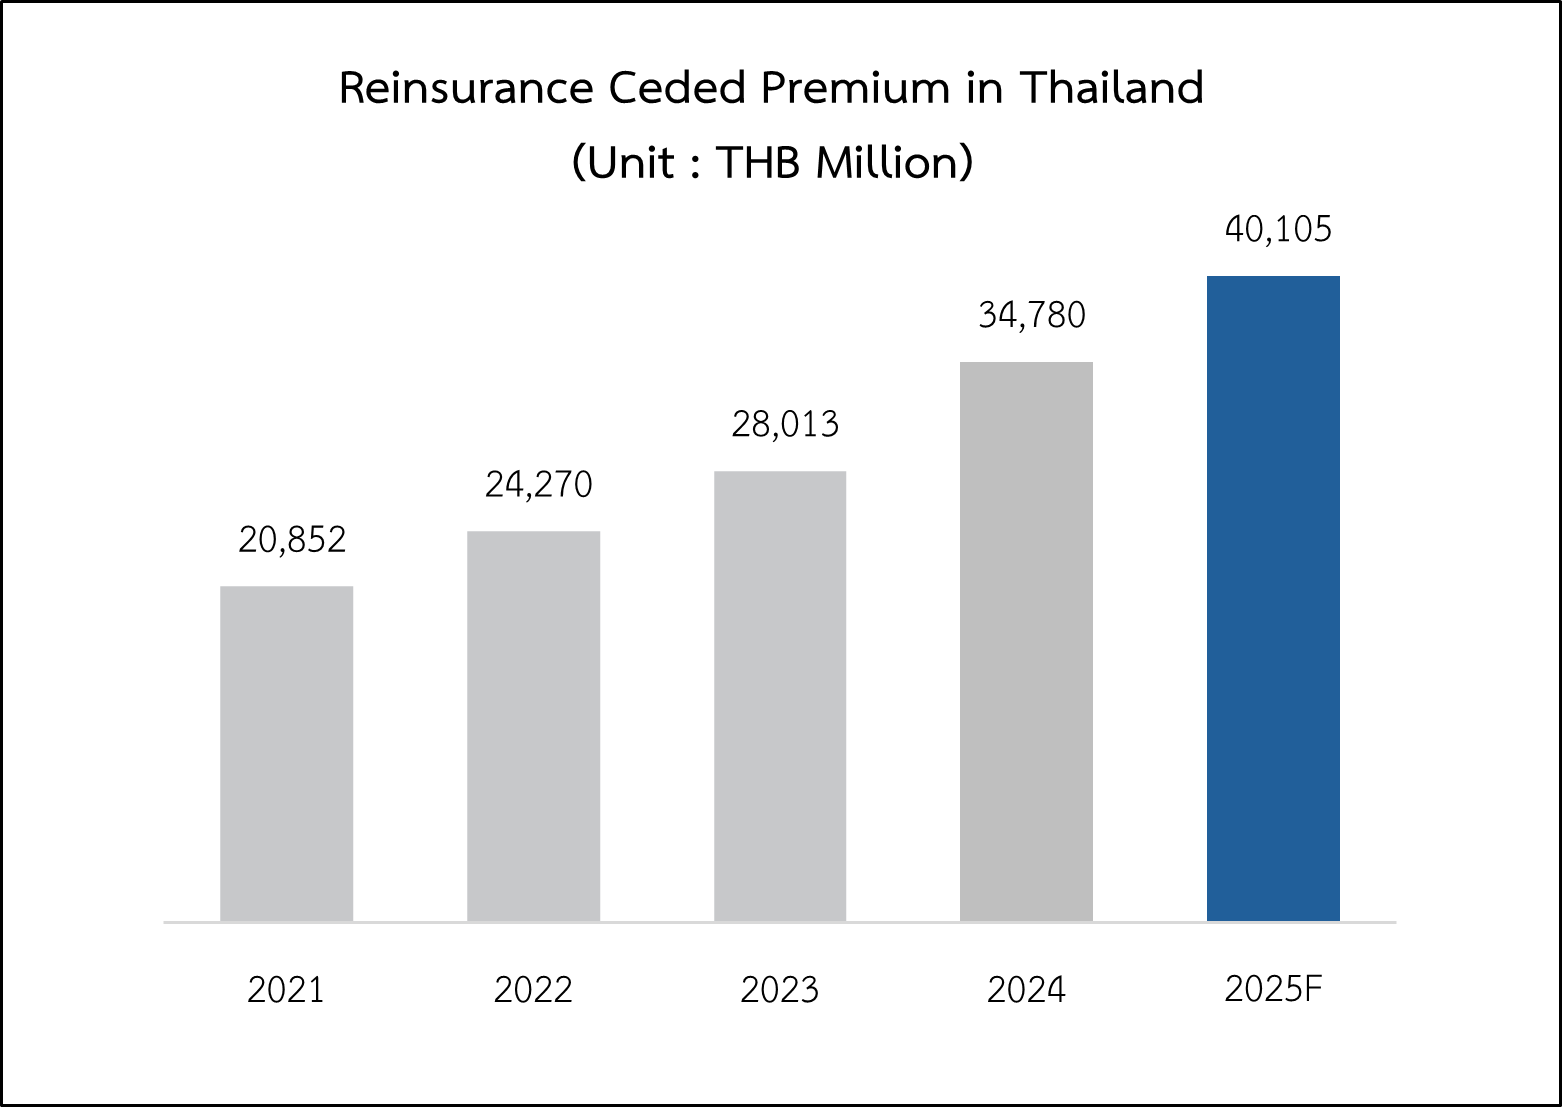
Source: Office of Insurance Commission/The Thai Life Assurance Association and the Company’s forecasts
Reinsurance premiums during 2023 – 2025
2025 | 2024 | 2023 | ||||
THB Million | Growth (percent) | THB Million | Growth (percent) | THB Million | Growth (percent) | |
Gross written premiums in Thailand | 676,505 | 3.5 | 653,923 | 3.2 | 633,445 | 3.7 |
Reinsurance ceded premiums in Thailand | 40,105 | 15.3 | 34,780 | 24.2 | 28,013 | 15.4 |
THREL’s gross written premium of domestic | 4,008 | -5.7 | 4,249 | 25.2 | 3,393 | 18.5 |
THREL’s market share from reinsurance ceded premium (percent) | 10.0 | 12.2 | 12.1 | |||
Source: Office of Insurance Commission/The Thai Life Assurance Association and the Company’s forecasts
Procurement of Products & Services
Reporting Mode
3117
Procurement (Overall)
The Company operates a life reinsurance business, with its primary source of funding derived from reinsurance premiums assumed. Such funds are managed and invested in accordance with the Company’s investment policy and Asset-Liability Management (ALM) framework to generate appropriate risk-adjusted returns consistent with the profile of reinsurance liabilities. The Company focuses on investing in high-quality assets with adequate liquidity and prudent diversification to support the timely settlement of claims and contractual benefits in the future.
As a regulated financial institution, the Company places strong emphasis on prudent capital and liquidity management. The capital structure is managed in line with the Company’s risk profile and business strategy, supported by a clearly defined investment policy under an appropriate risk management framework to ensure the Company’s ability to meet reinsurance obligations and withstand financial volatility.
The Company has established an Enterprise Risk Management (ERM) framework covering all material risk categories, with clearly defined risk appetite and relevant risk indicators. Risk exposures are regularly monitored, assessed and reported to the relevant committees to support effective risk management and sound corporate governance.
As of 31 December 2025, the Company’s Capital Adequacy Ratio (CAR) stood at 340.7%, above the minimum requirement prescribed by the Office of Insurance Commission (OIC), reflecting the Company’s strong capital position and its capacity to support sustainable long-term growth.
Product Information — Overview
Introduction
Characteristics of Business Solution and Innovation Development
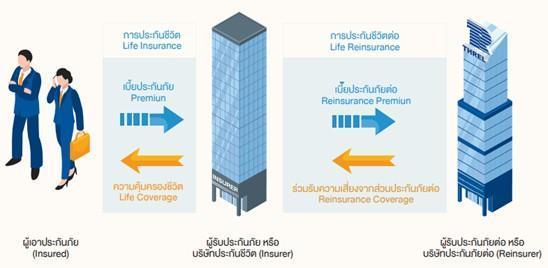
The Company’s core business has provided reinsurance service to support life insurance business for more than 20 years in aspect of risks transferred from life insurance companies; associated risk is shared by reinsuring the sum assured that stated in the life insurance contract. The products that could be reinsured varied from ordinary life insurance, group insurance, credit and mortgage term insurance, personal accident, health and accidental riders etc. Life Insurer companies would select a reinsurance service provider based on the following conditions.
Reputation, financial strength and strong credit rating
Reinsurance terms and conditions that meet the life insurance companies’ requirements such as underwriting guidelines, reinsurance agreement, reinsurance pricing and commission etc.
Factor from value added services that support business operations such as product development and underwriting consultation.
Satisfaction of high standard and timely services
Business Innovation development
Life insurance products & services development project
The company has collaborated with partners to develop health insurance products that provide mental health care coverage, both preventive and therapeutic, to meet the needs of modern consumers who are increasingly prone to illnesses caused by social and economic conditions that lead to stress.
The company develops cooperation with business partners, including foreign reinsurance companies. A group of brokerage companies, Third Party Administration (TPA) and healthcare Partners, to develop life insurance products. and increase your chances of getting work in new markets.
The company has been collaborating with “Pacific Life Re”, a reinsurance company in the Pacific Life group, a life and health insurance company from the United States, since 2022. In the past, they have jointly developed critical disease products and the Alternative Reinsurance Solution project, which raises the potential of the Thai life insurance industry. This collaboration will support our direction of creating sustainable growth.
Projects Under Construction
Has Projects Under Construction (Y/N)
No
Introduction
The company has no undelivered work because it is a reinsurance business.
Issuance of Other Securities
Introduction
The Company has not issued any preferred shares, debt securities or convertible securities that may affect rights of the shareholders.
Debentures & Bills of Exchange
Has Debentures (Y/N)
No
Convertible Securities
Has Convertible Securities (Y/N)
No